Digital Onboarding
-
How to Choose the Right Verification API Vendor
In today’s fast-paced digital economy, verification is more than a compliance requirement—it’s a cornerstone of trust, security, and business growth. From fintech platforms onboarding new users to HR tech companies verifying employment history, a robust verification process is essential. But implementing a verification system from scratch can be resource-intensive, slow, and error-prone. That’s why businesses…
-
How to Evaluate a Verification Stack: Questions Every CTO Should Ask
In the digital-first world, verification is no longer just a compliance checkbox—it’s the backbone of trust between your platform and its users. For neo-banks, fintechs, marketplaces, or any platform handling sensitive customer interactions, a robust verification stack can make or break the business. Yet, choosing the right stack is rarely straightforward. Technology evolves rapidly, data…
-
Best Video KYC Workflow for Personal Loan Apps
In India’s fast-moving digital lending space, personal loan apps face two big challenges: speed and trust. Borrowers want instant approvals and smooth experiences, while lenders need to verify identities, prevent fraud, and stay compliant. Video KYC has become the solution, replacing long, manual processes with a fast, secure, and regulatory-compliant alternative. But not all video…
-
Loan Origination System Integration with KYC APIs
In India’s fast-growing digital lending ecosystem, speed, compliance, and trust are critical. Borrowers expect instant approvals, seamless experiences, and secure handling of their personal information. Lenders, on the other hand, need to manage regulatory requirements, mitigate fraud, and make accurate credit decisions. In this delicate balancing act, a Loan Origination System (LOS) integrated with KYC…
-
KYB in the Age of Instant Business Onboarding
There was a time when onboarding a business meant paperwork. Stamped incorporation certificates.Physical visits.Board resolutions couriered across cities.Bank statements printed and signed. It was slow. Sometimes frustrating. But thorough. Today, a small business can apply for a loan, open a payment gateway, or get onboarded onto a marketplace in under fifteen minutes. No branch visit.No…
-
Video KYC for Lending Apps: Cut Drop-Off Without Risking Compliance
Every lending app eventually faces the same tension. On one side: growth.On the other: compliance. Marketing teams celebrate rising installs. Performance campaigns drive traffic at scale. Product dashboards show healthy loan applications started. And then — somewhere between document upload and identity verification — users disappear. Drop-off during KYC is one of the most expensive…
-
Difference Between KYC, eKYC, and Video KYC
Same regulatory objective. Three very different execution models. If you work in fintech, lending, NBFCs, payments, or any regulated digital business, you’ve probably heard these terms used almost interchangeably: KYC, eKYC, Video KYC. They’re related. But they are not the same. And the difference isn’t just technical. It affects onboarding speed, fraud exposure, regulatory defensibility,…
-
Asset Verification APIs for Sharing Economy Platforms
The sharing economy operates on distributed ownership. Vehicles are listed by individuals. Properties are rented peer-to-peer. Equipment, devices, warehouses, workspaces, and tools move through decentralized networks of suppliers. The platform facilitates the transaction — but it does not control the asset. Yet the platform carries the risk. Fraudulent listings, expired compliance, ownership disputes, asset misrepresentation,…
-
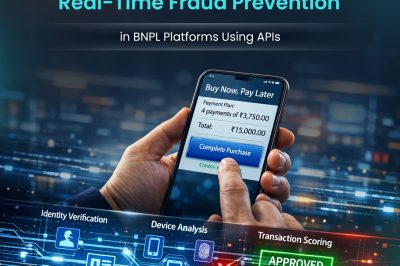
Real-Time Fraud Prevention in BNPL Platforms Using APIs
Buy Now, Pay Later didn’t grow slowly. It exploded. From checkout pages on fashion websites to electronics marketplaces and travel portals, BNPL has quietly embedded itself into everyday spending behavior. For customers, it feels frictionless. For merchants, it boosts conversion. For platforms, it unlocks scale. But underneath that smooth checkout button sits a hard reality:…
-
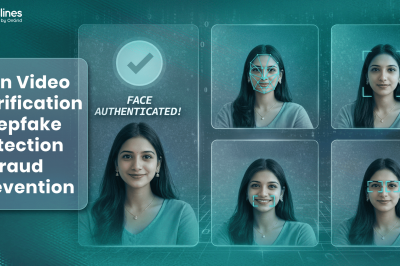
AI in Video Verification: Deepfake Detection & Fraud Prevention
There was a time when a simple webcam selfie felt like enough proof of identity. A quick live video chat to show a photo ID and a smile — that was trust. Not anymore. Today, faces can be generated by code. Voices can be cloned with a few seconds of audio. Entire video streams can…
Recent Posts
- eKYC in India: How Digital Identity Verification Is Changing Customer Onboarding
- Customer Profiling for BFSI: Going Beyond Traditional KYC
- How to Simplify Delivery Partner Onboarding, Verification and Lifecycle Management
- Merchant Onboarding: A Complete Guide to KYC, Risk Management & Payouts
- Video PD for Loans: Faster Borrower Assessment and Underwriting
Categories
- APIs 69
- BFSI 98
- Digital Onboarding 107
- Gridlines 50
- Industry Insights 78
- KYB 14
- MSME 10
- Uncategorized 1
Tags
#GridlinesAPI address verification api AI in Fraud Detection aml API Integration APIIntegration Background check Business Verification digital KYC Digital Onboarding eKYC Employment Verification financial services fintech Fintech Solutions Fraud Prevention gridlines Gridlines API identity verification insurance kyc KYC API Last-Mile Delivery Security lending Prevent Delivery Fraud RC verification TrustEstablishment underwriting Verification video kyc